Order Book Insights: Mapping Momentum Changes in Live Betting Exchanges
Ben Schwarz · Jul 22, 2026
Order Book Insights: Mapping Momentum Changes in Live Betting Exchanges
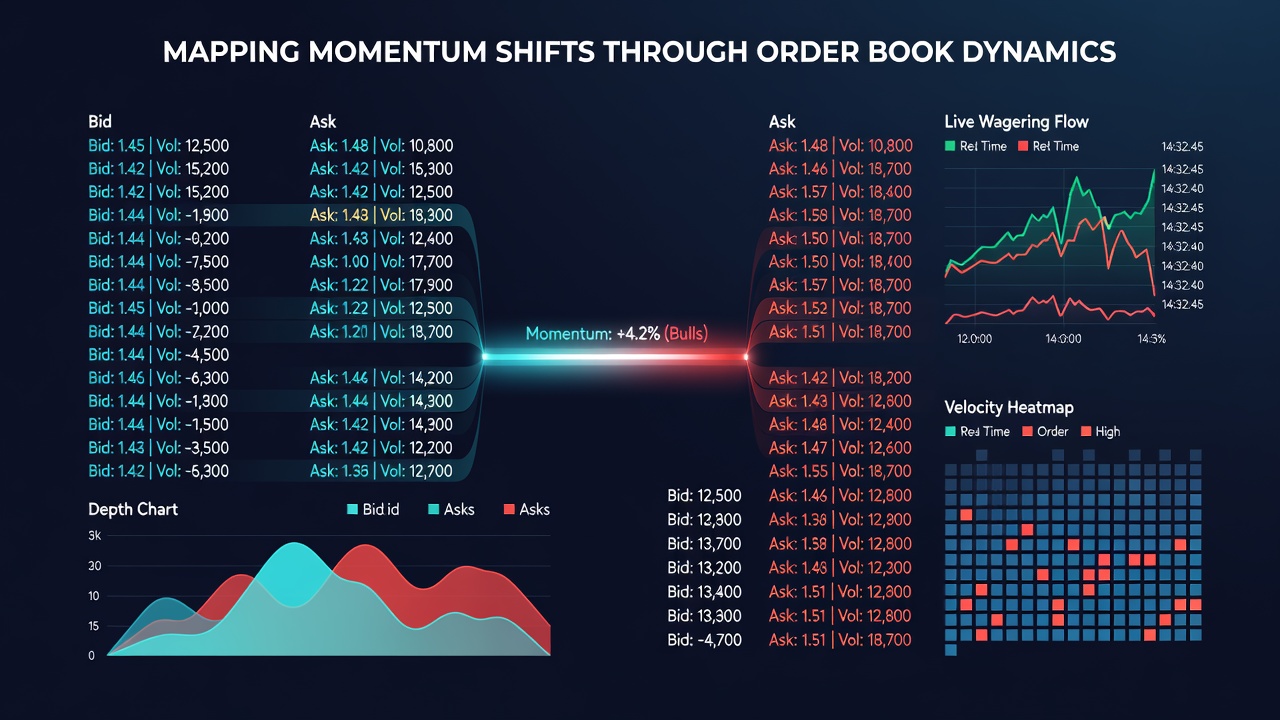
Live wagering platforms operate through order books that list unmatched bets at various odds levels, creating a visible structure of supply and demand for each outcome in real time. Traders monitor these layers to identify when liquidity concentrates on one side of the book or when large orders begin to pull prices in a particular direction. Data from exchange operators shows that volume spikes at specific price points often precede visible price movements, allowing participants to track momentum before it appears in the final settled odds.
Core Components of Wagering Order Books
Each order book displays back and lay prices alongside the amounts available at those levels, with updates arriving continuously as new orders enter or existing ones get matched. Researchers at institutions studying financial market analogs note that depth, which measures the total stake visible at each price, provides a direct indicator of support or resistance similar to equity markets. When depth thins on one side while accumulating on the other, the imbalance frequently signals an impending shift that algorithms and manual traders alike attempt to capture.
Time and sales data, which records every matched transaction, further refines this picture by revealing the pace at which liquidity disappears. Observers note that clusters of large matches occurring within seconds often coincide with news events or in-play developments, accelerating the rate at which prices adjust across the book.
Detecting Momentum Through Liquidity Patterns
Momentum shifts become visible when successive layers of the order book erode faster than they replenish, a process analysts track using metrics such as cumulative volume delta. Studies of exchange data demonstrate that sustained one-sided absorption, where large bets remove liquidity without immediate replacement, precedes price acceleration in the same direction. Platforms record these sequences across thousands of events monthly, producing datasets that quantitative teams use to calibrate detection models.
Price ladder visualizations allow participants to watch the book evolve tick by tick, highlighting when resting orders move or cancel in response to incoming flow. Those who have examined these patterns across multiple sports find that certain sequences, such as repeated hits against a single price level followed by rapid depletion of the opposite side, repeat across different match types and time zones.
Platform Tools and Data Feeds
Modern wagering interfaces supply depth-of-market feeds that stream full order book snapshots at sub-second intervals, enabling third-party software to calculate derived indicators like order flow imbalance or micro-price changes. According to reports from the Australian Gambling Research Centre, operators increasingly integrate these feeds with historical archives so users can compare current dynamics against similar past situations. Such comparisons help isolate whether current liquidity patterns align with previously observed momentum reversals or continuations.
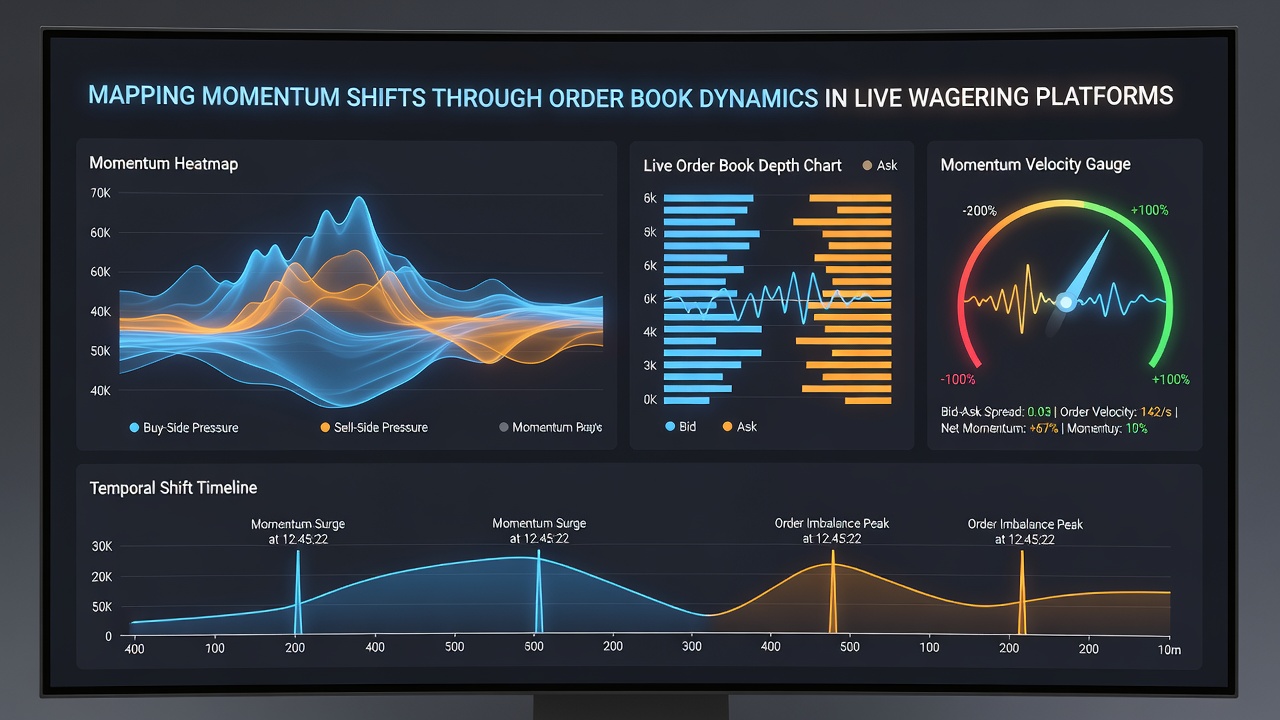
Some platforms expose application programming interfaces that let custom scripts monitor specific price bands or trigger alerts when volume thresholds are crossed. Industry documentation indicates that these APIs handle millions of updates per hour during peak sporting calendars, requiring robust infrastructure to maintain accuracy and low latency for all connected users.
Research Findings on Order Flow Predictability
Academic examinations of betting exchange records reveal measurable autocorrelation between order book imbalances and subsequent price movements lasting from several seconds to a few minutes. A working paper hosted by the National Bureau of Economic Research examined thousands of soccer and tennis markets and found that initial absorption of large back orders tended to produce continued price drift in the same direction more often than random chance would predict. The analysis controlled for event-specific factors such as score changes and time remaining, isolating the contribution of order flow itself.
Market participants who aggregate these signals across correlated events, such as simultaneous tennis matches on the same surface, report improved consistency in identifying when one market's momentum is likely to influence related books. Data aggregated over multi-month periods shows that cross-market spillovers appear most reliably during high-liquidity windows when overlapping events draw concentrated trading activity.
Practical Applications in July 2026 Calendars
With major tournaments scheduled throughout July 2026, exchange operators have reported elevated message rates as traders position ahead of extended sessions. Order book monitoring during these periods highlights how overnight liquidity gaps can create pronounced momentum once trading resumes, particularly in markets that carry overnight risk from weather or lineup announcements. Firms providing analytics services update their reference datasets weekly to incorporate the latest event types and venue characteristics observed in the current season.
Conclusion
Order book dynamics supply a continuous stream of observable data that market participants use to track momentum shifts across live wagering platforms. Depth measurements, transaction records, and derived imbalance metrics together form a framework that researchers and practitioners apply to historical and real-time contexts alike. As data feeds and analytical tools continue to evolve, the granularity available for mapping these shifts increases, supporting more precise identification of liquidity patterns that precede price adjustments in competitive markets.